
- Drax expects 2026 adjusted EBITDA near the top of analysts’ £680-711mn range.
- Its £561mn purchase of Bluefield Solar Income Fund adds 0.9 GW of operating solar and wind and a 2.9 GW development pipeline.
- The acquisition broadens Drax’s technology mix, but increases leverage and does not remove its continued dependence on biomass policy.
Drax has upgraded its full-year earnings outlook after strong summer trading and the completion of its takeover of Bluefield Solar Income Fund (BSIF), as the generator begins integrating solar, wind and battery development into a business historically dominated by biomass and flexible generation.
The company now expects adjusted EBITDA for 2026 to be around the top of analysts’ consensus range of £680mn to £711mn. The improvement includes BSIF’s contribution from 1 August and stronger-than-expected performance during July and August, when Drax said its assets provided system support through the summer heatwave.
Chief executive Will Gardiner said the group was “transitioning Drax into a broader business at the heart of the UK energy system”.
“This is an exciting time for Drax and through our plans for solar, batteries, OCGTs, hydro and 4 GW of grid access at our Selby site, we are helping to drive economic growth across the country and support jobs, aligned to the priorities of the UK government,” he said.
The company completed its acquisition of BSIF on 31 July for £561mn, implying an enterprise value of £1.082 billion. The portfolio contains about 0.8 GW of solar and 0.1 GW of onshore wind across more than 250 assets in England, Scotland, Wales and Northern Ireland.
It raises Drax’s total capacity under management to approximately 6.1 GW and creates a new Solar & Wind reporting division from 2027.
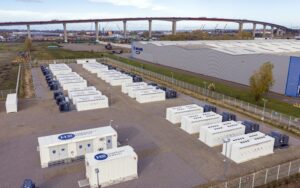
BSIF also brings a 2.9 GW gross development pipeline, comprising roughly 2 GW of battery storage and 0.9 GW of solar. Around 0.5 GW of that solar capacity already holds 15 to 20-year Contracts for Difference (CfDs) at inflation-linked strike prices of approximately £69/MWh to £74/MWh in 2026 money. Some 0.2 GW is in near-term development, although final investment decisions remain outstanding.
Not yet a clean break
The strategic logic is to combine contracted renewables with Drax’s trading, optimisation and flexible generation platform. The company expects better route-to-market pricing, lower balancing costs and savings from delisting BSIF and bringing management functions onto its existing platform.
Its trading update also points to a wider integrated model: intermittent solar and wind production; batteries, pumped hydro and gas assets capable of responding to market conditions; and an energy solutions business that already provides route-to-market services to around 2,000 small renewable assets.
That model is increasingly attractive as the GB system adds variable generation and places greater value on flexibility. BSIF’s existing inflation-linked revenues also improve earnings visibility, while its battery pipeline offers exposure to balancing and intraday volatility.
The balance sheet is the immediate test. Drax drew £800mn under a bridge facility to complete the acquisition and repay £300mn of BSIF debt. Net debt-to-EBITDA is expected to move above the company’s long-term target of approximately two times during 2026, before returning to that level by the end of 2027. The bridge loan still needs to be refinanced.
Drax’s transition should not be mistaken for an exit from biomass. Its four units at Selby remain covered by a new low-carbon dispatchable CfD from April 2027 to March 2031, and the group has now substantially contracted the external biomass required over that period.
Biomass remains a politically hot potato. A Public Accounts Committee report in April 2025 criticised the historic sustainability assurance regime, the absence of competition in the new support agreement and the price paid for Drax’s dispatchable output. Drax says the new contract includes enhanced monitoring, auditing and a requirement for all fuel to be sustainably sourced.
The investment case is consequently shifting rather than being replaced. Drax is building a more diversified portfolio with exposure to renewables and flexibility, but biomass continues to provide earnings, cash flow and regulatory risk. The success of the BSIF deal will be measured by whether Drax can convert that cash flow into lower-risk growth without overextending its balance sheet.